Inside Insight Partners: Devin Parekh on AI Valuations, Liquidity Realities, and Twenty-Six Years of Macro Adaptation

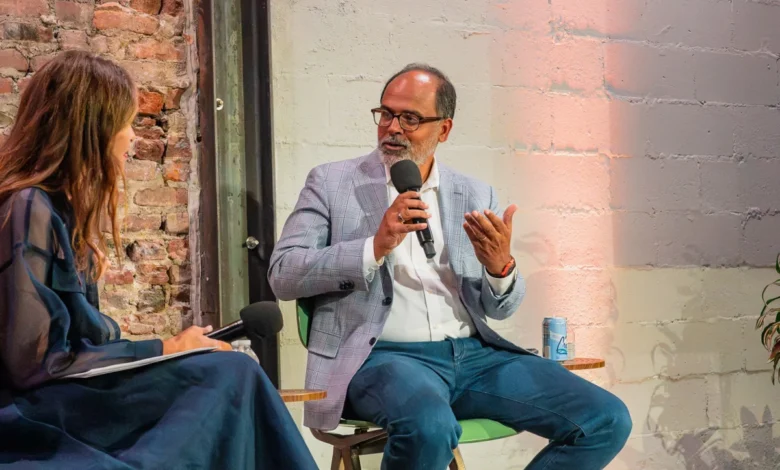
The venture capital ecosystem is frequently dominated by the loudest voices in the room—those who cultivate massive followings on social media platforms and treat podcast appearances as a primary business development tool. Yet, away from the digital spotlight, heavyweight investment firms continue to deploy tens of billions of dollars quietly, relying on historical performance rather than public fanfare to justify their market standing. Devin Parekh, who has co-run the global software investment giant Insight Partners for 26 years, embodies this understated ethos. Managing a portfolio backed by roughly $90 billion in assets under management (AUM), Parekh stepped into the spotlight during a recent sit-down interview at the StrictlyVC event in New York City, offering a rare, candid assessment of the venture capital landscape.
The conversation traversed a broad spectrum of industry-defining topics, including the explosive growth of frontier artificial intelligence labs, the pragmatic realities of returning capital to limited partners (LPs), shifting global talent corridors, and the mathematical limitations of modern tech valuations. By stripping away the hyperbolic rhetoric that often characterizes discussions surrounding emerging technology, Parekh provided a masterclass in institutional investment discipline.
Main Facts and the Understated Philosophy of Insight Partners
Insight Partners has long operated as a titan in global software investing, maintaining positions in foundational pillars of the modern tech stack, such as Databricks, alongside multi-billion-dollar stakes in frontier AI giants OpenAI and Anthropic. Despite its immense capital footprint, the firm deliberately maintains a low public profile.
During the New York event, Parekh addressed this strategic silence directly, contrasting Insight’s methodical approach with the pervasive tendency of modern venture capitalists to weigh in on macroeconomic and geopolitical events far outside their core competencies.
“Every venture capitalist thinks they’re an expert on everything now—epidemiology during COVID, geopolitics during the war,” Parekh noted. “I’m not sure we’re all experts on everything. Our attitude has been: Let the portfolio do the talking. We’re investing in founders and companies. We have to communicate enough that people know who we are, but our performance should speak for itself.”
This philosophy extends to how the firm structures its global deployment strategy. Rather than adhering to rigid geographic or strategy allocations, Insight treats capital deployment as a temporal and fluid process. Spanning early-stage venture capital, growth equity, and late-stage buyouts, the firm evaluates macro conditions continuously. However, high interest rates, restrictive software debt markets, and compressed exit multiples have temporarily sidelined major buyout activities, with Insight refraining from executing a large-scale buyout since 2024.
Chronology and Evolution of Software Valuation Cycles
To understand Insight’s current positioning, one must examine the broader historical trajectory of private market valuations over the past half-decade. The zero-interest-rate policy era of 2020 and 2021 created an unprecedented valuation bubble, characterized by rapid funding rounds that frequently bypassed fundamental financial metrics. Following the macroeconomic correction of 2022 and 2023, the industry experienced a prolonged dry spell in liquidity, leaving many emerging funds unable to return capital to their limited partners.
In the contemporary market, valuation velocity has reemerged, echoing the speculative frenzy of 2021. Traditionally, a follow-up funding round is justified by incoming operational data that reduces risk for the investor, thereby commanding a higher price. Today, however, many venture rounds close with such velocity that incremental data is virtually nonexistent. Investors are effectively paying higher prices without a corresponding reduction in risk.
Insight’s response to this velocity has been to pivot strategically toward earlier-stage investments. By deploying capital via a scale fund—writing checks in the $20 million to $25 million range rather than committing half-billion-dollar blocks—the firm mitigates initial risk while preserving the optionality to double down on proven winners. This methodology was memorably demonstrated in the firm’s trajectory with cybersecurity unicorn Wiz, where an initial Series A check was followed by successive rounds, resulting in massive valuation gains that would have been unattainable had the firm walked away after its first ticket.
Supporting Data and Portfolio Concentration Risks
The modern venture capital ecosystem is increasingly defined by extreme capital concentration. Industry data from the first half of the year indicates that approximately half of all venture capital dollars deployed went directly into a handful of frontier AI labs, primarily OpenAI and Anthropic. This trend has sparked intense debate among limited partners regarding concentration risk.
While some prominent venture firms, such as Founders Fund and Thrive Capital, have successfully implemented highly concentrated strategies, Parekh emphasizes that Insight’s historical data across thirteen funds strongly favors diversification.
“In this particular moment, if 25% of our fund were in Anthropic, our returns would look better,” Parekh acknowledged. “But data over time doesn’t support excessive concentration, and most LPs don’t want that exposure either… We’re on fund 13, so we have to think in terms of ten funds, not one.”
This diversified framework has not prevented Insight from securing stakes in both OpenAI and Anthropic—a dual investment strategy that was once considered an absolute taboo due to competitive conflicts of interest. Parekh explained that the viability of investing in rival foundational models depends heavily on the investment stage. At early stages, such as a Series A or B, stringent information-sharing barriers prevent direct exposure to competing entities. However, at later stages, when investors sit outside the boardroom and hold no governance responsibilities, the transaction resembles the acquisition of a publicly traded stock, where OpenAI serves as the dominant consumer play and Anthropic commands a distinct enterprise strategy.
Global Talent Corridors and Geographic Nuances
The geographical distribution of technological talent has undergone a profound transformation. Historically anchored strictly to Silicon Valley, elite engineering and commercial talent has become geographically dispersed across global hubs.
Illustrating this shift, Insight recently competed for Legora, a buzzy European AI legal-tech company headquartered in Stockholm. In a testament to the borderless nature of modern software talent, Insight partner Jeff Horing flew directly to Sweden to pitch the founders, though the firm ultimately lost the deal to General Catalyst.
Nevertheless, certain technology sectors maintain stark geographic clustering. Artificial intelligence infrastructure talent remains heavily concentrated in San Francisco. Conversely, vertical AI applications tied to financial services, such as Ramp, remain anchored in New York. Consequently, vertical AI investing allows for greater geographic diversification than pure infrastructure plays.
Physical AI and the Reality of Robotics
While software applications and foundational models dominate tech headlines, physical artificial intelligence—the intersection of AI and robotics—remains a subject of intense internal and external debate.
Despite enthusiasm from younger investors who view physical intelligence as the next major frontier, Insight maintains a cautious posture. Parekh categorizes most physical intelligence enterprises as sophisticated science projects. Evaluating these companies requires compounding two distinct risk factors: determining whether large-scale robotics adoption will occur, and accurately timing when that adoption will materialize. While the firm actively monitors the space, it has deliberately chosen to remain on the sidelines until the unit economics and market readiness align more definitively.
Liquidity Realities and the Imperative of DPI
A central challenge facing the broader venture capital industry is the chronic lack of DPI (Distributed to Paid-In capital)—a critical metric measuring actual cash returned to limited partners relative to the capital they invested. Many first- and second-time funds raised during the 2021–2023 window have struggled to return capital, threatening their ability to raise subsequent funds.
Parekh stresses that returning capital is the foundational mandate of professional asset management. Over the preceding two years, Insight successfully returned more than $20 billion to its LPs via strategic sales and initial public offerings, with additional billions expected in the pipeline.
This emphasis on liquidity extends directly to how Insight advises the founders within its portfolio. When founders receive acquisition or secondary offers at frothy valuations, the firm frequently encourages them to de-risk by taking 10% to 20% off the table.
“You can’t compound $40 billion at 50% every two months for two years without becoming the world economy,” Parekh noted, highlighting the mathematical impossibility of perpetual exponential growth. De-risking protects both founders and investors against inevitable market corrections.
Broader Impact and Implications for Public Markets
As the horizon looks toward potential public market debuts from tech behemoths like Anthropic and OpenAI—both of which have scaled to unprecedented valuations within remarkably short timeframes—the broader implications for public equity markets are profound.
Anthropic, achieving a massive operational footprint within four years of inception, signals a shifting paradigm where private markets retain companies that historically would have been publicly traded years earlier. When generational enterprises cross the public threshold at market caps exceeding one trillion dollars, public-market investors must recalibrate their return expectations.
Ultimately, Insight Partners’ longevity across twenty-six years and thirteen funds underscores a timeless investment truth: while speculative cycles and technological shifts will perpetually disrupt the status quo, disciplined portfolio construction, active liquidity management, and a relentless focus on fundamental metrics remain the ultimate arbiters of sustainable venture capital success.
Related posts: