Graduate Student Loan Limbo: How Regulatory Uncertainty is Reshaping Higher Education Financing

As the new academic year begins, Mitzie Westgate, a senior at the College of Charleston, finds herself in a position shared by thousands of students across the United States: stuck in a state of suspended animation regarding her future. An exercise science major with aspirations of pursuing a doctorate in occupational therapy to establish a nonprofit for children with disabilities, Westgate’s roadmap to graduate school has been derailed by profound confusion surrounding federal student loan regulations. With her graduation approaching next spring, she remains unable to determine which universities are financially viable, as shifting federal policies threaten to drastically reduce the amount of capital available to students seeking advanced degrees.
The current atmosphere of uncertainty stems from a recent legislative shift that removed dozens of graduate-level programs from the U.S. Department of Education’s classification of "professional" degrees. This reclassification has imposed stringent caps on the federal loans available to graduate students. For students like Westgate, this means the prospect of financing an advanced degree is no longer a matter of simple arithmetic, but a complex gamble against a backdrop of potential debt, private lending traps, and a legal system currently in flux.
The Legislative Shift: From Grad PLUS to Restricted Limits
For years, the Grad PLUS loan program acted as a critical financial bridge for graduate students, allowing them to borrow up to the full cost of attendance, as determined by their university. This flexibility ensured that students pursuing high-cost, essential degrees—particularly in the health care and social service sectors—could complete their education regardless of their personal financial background.
However, a legislative change that took effect on July 1, 2026, fundamentally altered this landscape. The new regulations eliminated the open-ended nature of Grad PLUS loans, capping federal borrowing at $20,500 per year and $100,000 in total for the majority of graduate programs. Only 11 specific "professional" programs were granted higher, yet still finite, limits of $50,000 annually and $200,000 in total.
The rationale behind these caps, as argued by some policymakers, is to curb the skyrocketing cost of graduate tuition and mitigate the student debt crisis by limiting the availability of easy federal credit. Yet, the implementation has been anything but smooth. A lawsuit brought forth by a coalition of nursing groups, health care organizations, and educational associations successfully prompted a federal judge to suspend the restrictive rules until at least December. This temporary injunction has created a "policy vacuum," leaving students to apply for graduate programs while being unable to ascertain what their actual borrowing capacity will be for the 2027-28 academic year.
The Domino Effect on Health Care and Human Services
The sectors most impacted by these changes are those that the country relies on most: nursing, psychology, social work, and occupational therapy. These fields are characterized by high tuition costs but, in many instances, modest starting salaries.
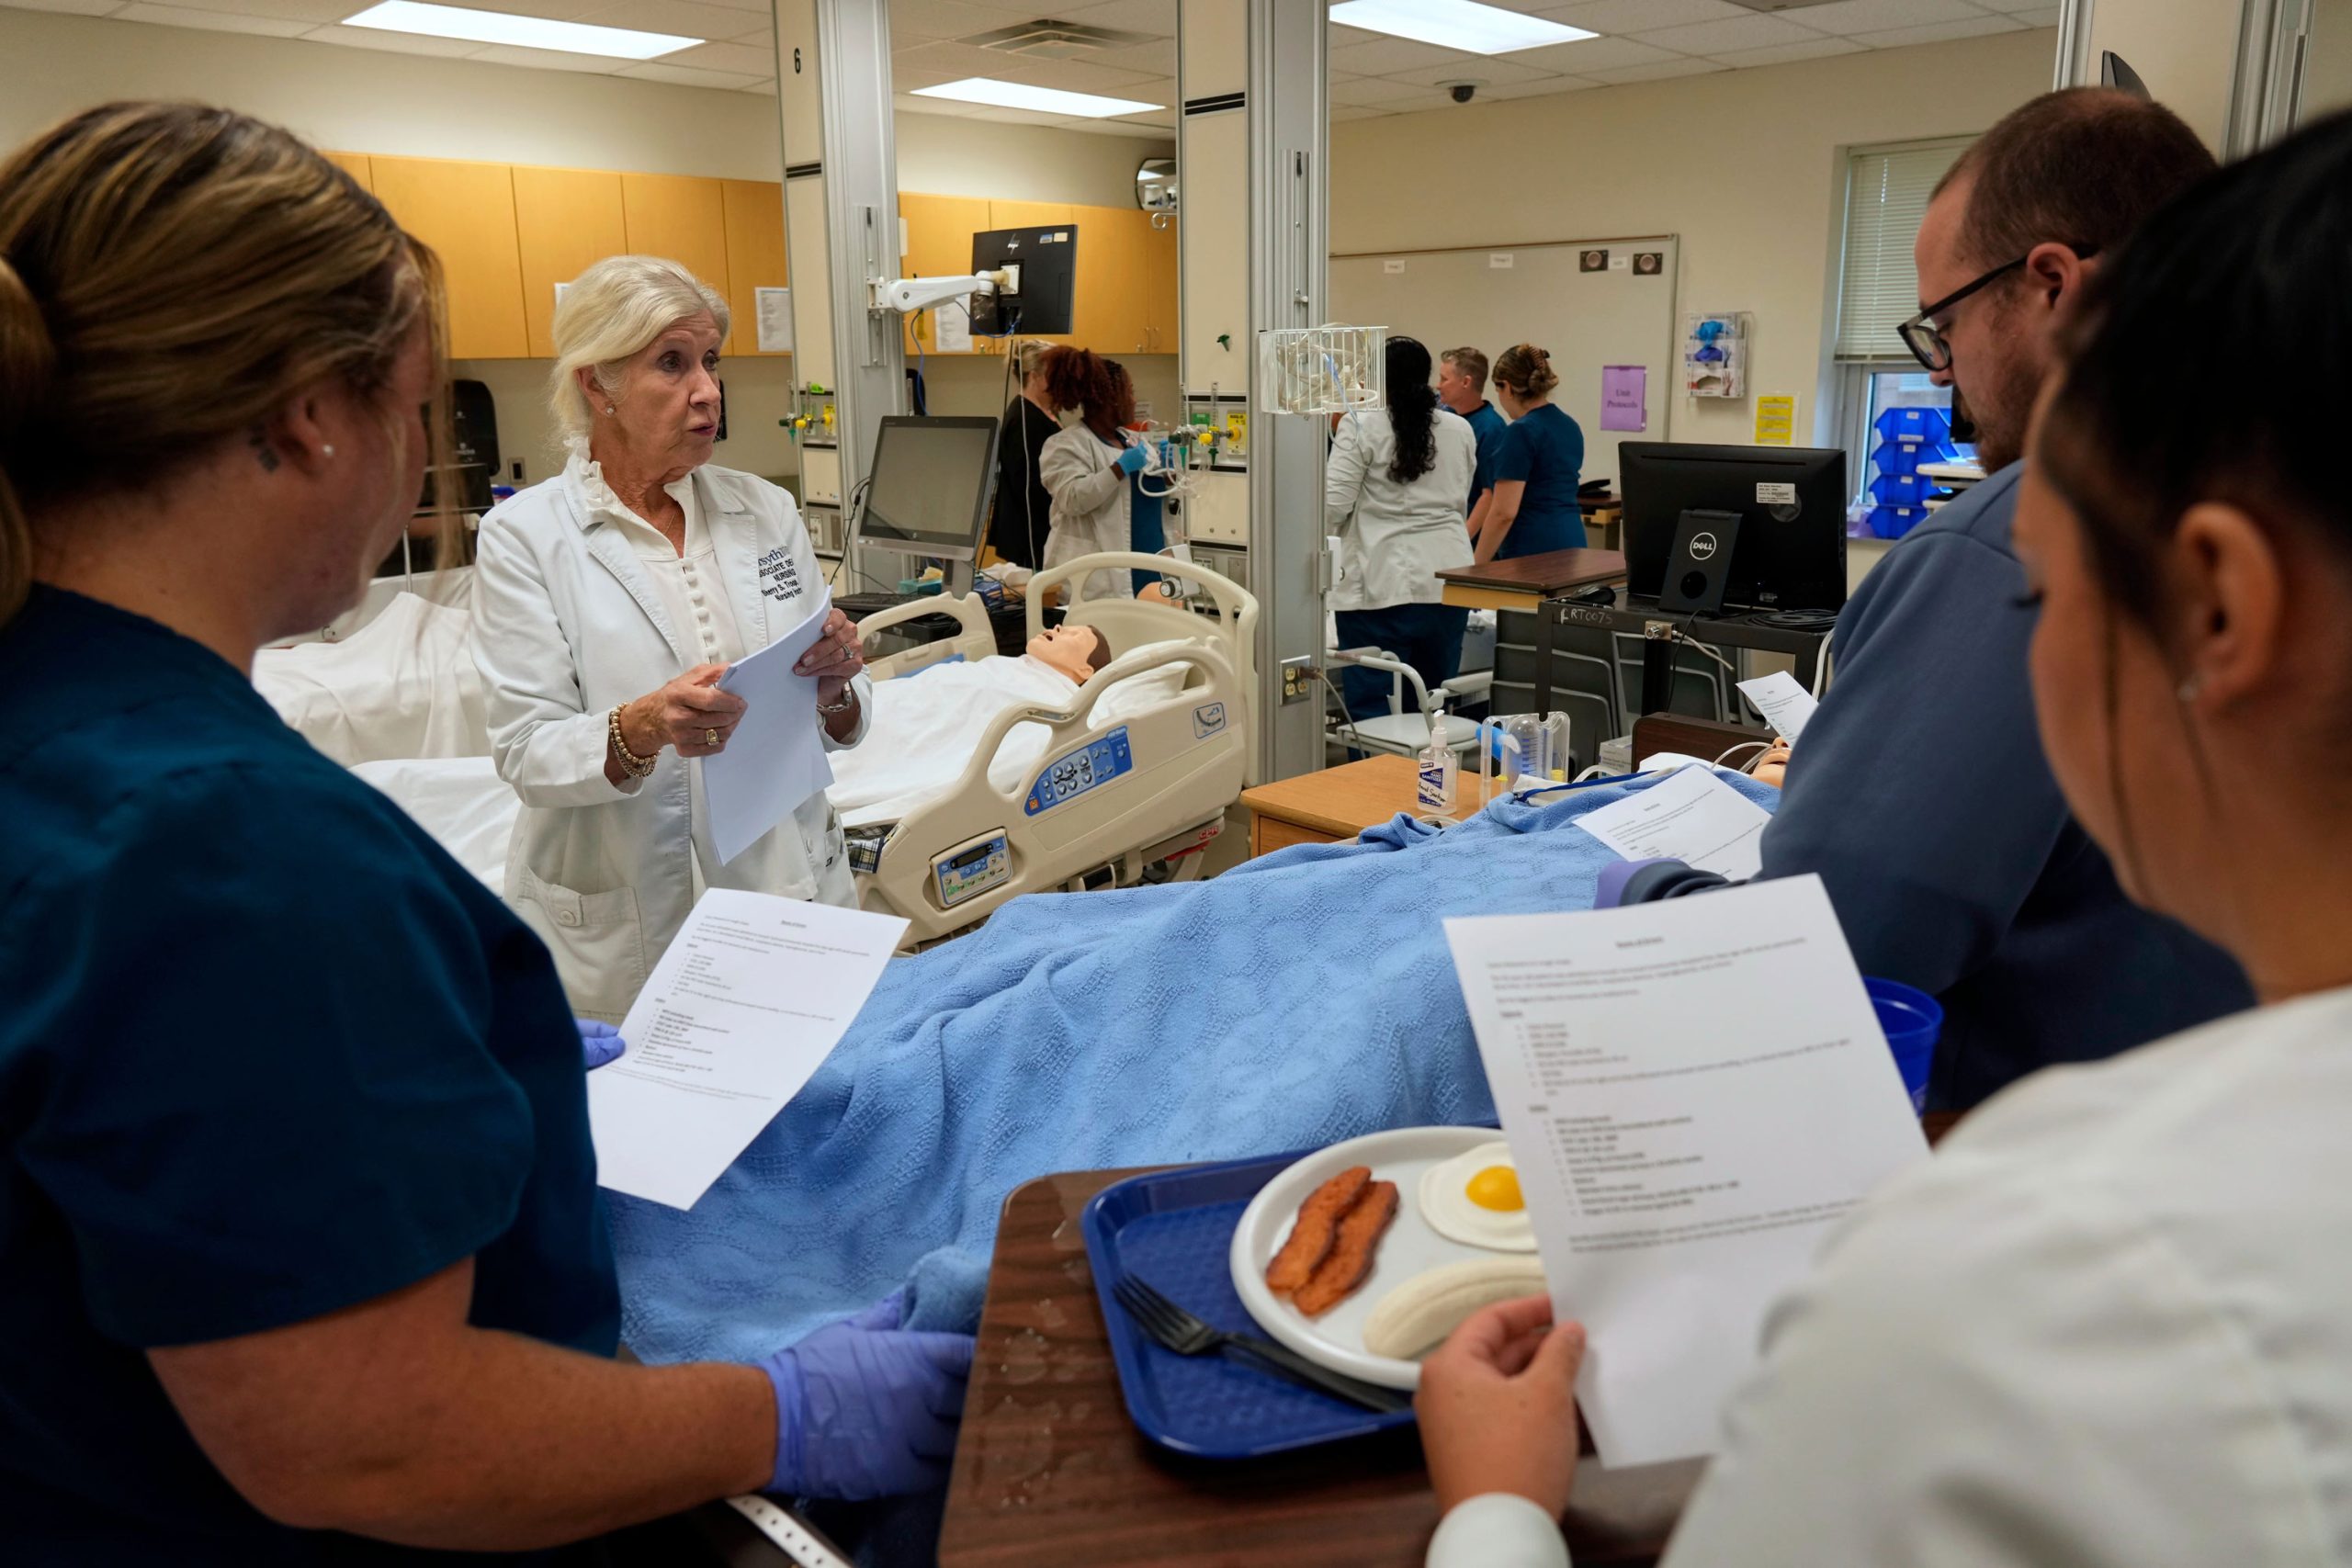
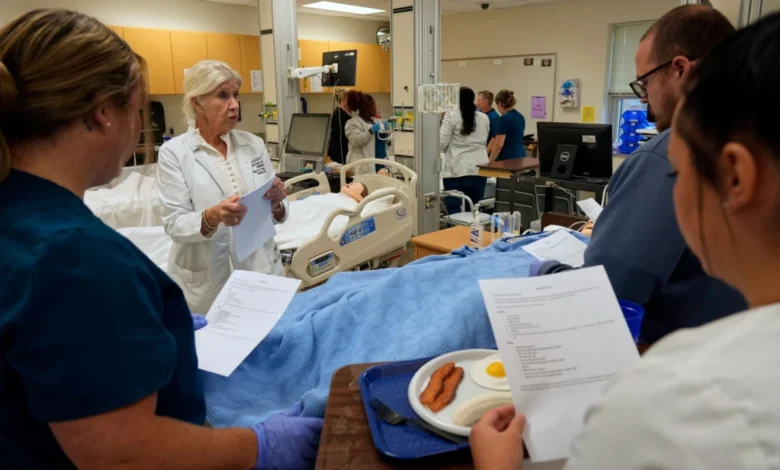
Kayce Cordray, a 44-year-old doctoral student in nursing practice at Oral Roberts University, serves as a poignant example of the potential fallout. While she is currently grandfathered into previous lending rules, she views the new limitations as a systemic threat to the nursing profession. "It truly does limit the people who can complete their degrees," Cordray noted. "We are facing a real nursing shortage and a real rural health care shortage. We’re not even going to be able to get registered nurses if we don’t have faculty. It’s a domino effect."
The implications extend to the diversity and accessibility of the workforce. If graduate education becomes a privilege reserved for those with existing personal wealth or high creditworthiness, the pipeline to critical public-facing roles may shrink. This disproportionately affects non-traditional students, such as parents balancing school with family obligations, who cannot rely on part-time employment to bridge the massive gap left by the reduction in federal aid.
The Private Lending Frontier: Risks and Realities
With federal options narrowing, students are increasingly looking toward private lenders to cover the deficit. However, this shift comes with significant risks. Financial aid experts warn that private lenders operate under different mandates than the federal government. They prioritize profitability and risk management, which means they are likely to shy away from students pursuing degrees with lower earning potential or those with less-than-perfect credit histories.
Mark Kantrowitz, a prominent authority on student financial aid, observes that private lenders are increasingly targeting students enrolled in programs that promise high, immediate financial returns—such as medical or law school—while avoiding those in the helping professions. "From the marketing that I’ve seen from lenders, they’re trying to target grad students who are likely to be lucrative," Kantrowitz stated.
Furthermore, there is a legitimate concern regarding predatory practices. Eileen Connor, director of the Project on Predatory Student Lending, warns that the removal of various federal guardrails during the current administration could leave students vulnerable to unfavorable loan terms. "There’s a lot of different ways these loans can have traps," Connor explained, citing hidden fees and mandatory arbitration clauses that preclude students from seeking legal recourse in the event of disputes. With interest rates for private loans potentially soaring as high as 16% for high-risk borrowers, the financial burden could become a lifelong anchor for graduates.
Institutional Responses and Economic Analysis
The reaction from universities has been varied. Some wealthier institutions have begun to step into the void by offering institutional, low-interest loans to bridge the gap for their graduate students. Others have established lists of "preferred lenders" to guide students toward more reputable financial institutions.
There is a ongoing debate among economists regarding whether these loan caps will actually force universities to lower their tuition rates. Sarah Sattelmeyer, director of education, opportunity, and mobility at the New America think tank, remains skeptical. "Right now I don’t see evidence that we’re going to see large across-the-board tuition and price reductions," she said.

Conversely, some analysts at the American Enterprise Institute suggest that market forces may eventually dictate lower prices. Preston Cooper, a senior fellow at the institute, argues that if a university’s tuition exceeds what a student can reasonably borrow—and if those students choose to attend cheaper, rival institutions—the high-priced schools will face significant pressure to lower their costs to remain competitive. He points to the disparity between elite institutions like the University of Pennsylvania and their more affordable regional counterparts as evidence that a shift in consumer behavior could force a reevaluation of graduate school pricing models.
The Human Cost of Policy Uncertainty
For students like Gracie Hayworth, who is currently enrolled in an online master’s program at Dartmouth, the uncertainty is not just a policy concern—it is a life-altering factor. As she and her husband plan their future trajectories toward doctorates, they are forced to weigh the long-term impact of potential private debt. Federal loans generally offer a grace period for repayment until after graduation, whereas private loans often require immediate repayment, creating a significant barrier for those still in the classroom.
"We were sitting at the kitchen table deciding whether we can make this work," Hayworth said. "If he has to pay those loans while he’s still in school, that adds another barrier."
As the December deadline for the judicial review of the loan rules approaches, students, financial aid directors, and university administrators remain in a state of high alert. Megan Walter of the National Association of Student Financial Aid Administrators aptly describes the situation as a "policy vacuum" defined by professional "whiplash." For the thousands of students currently in the application cycle, the outcome of this legal and legislative battle will determine far more than their choice of university—it will define the economic reality of their professional lives for decades to come.
As for Mitzie Westgate, the path forward remains obscured. While she continues to prepare her applications, she acknowledges that the final decision will be dictated by necessity rather than preference. "It’s kind of up in the air whether I’ll be able to pay for college" after this year, she admits, highlighting the precarity of a system that is currently failing to provide the stability required for the next generation of professionals to plan their futures.
Related posts: