Rocket Report Edition 9.17: Space Industry Shifts as New Players Emerge and Legacy Partnerships Fray

The global aerospace landscape is undergoing a period of profound structural realignment, marked by the emergence of ambitious startups, the modernization of existing launch infrastructure, and an increasingly strained relationship between government agencies and their primary commercial contractors. As the demand for orbital access continues to outpace available launch capacity, the sector is seeing a surge in investment and a race to field medium-lift capabilities. While established giants like United Launch Alliance (ULA) work to stabilize their flight manifests, new entrants such as Cowboy Space are attempting to disrupt the status quo, even as industry veterans warn of a potential supply crunch that could persist well into the next decade.
The Rise of Cowboy Space and the Big Iron Launcher
This week, the nascent startup Cowboy Space, led by former Robinhood founder Baiju Bhatt, made a significant splash by unveiling the technical specifications for its proposed medium-lift launch vehicle, "Big Iron." The announcement, held in Palo Alto, California, marks a rare entry into the medium-lift market, a segment traditionally dominated by high-reliability incumbents. Named after the Marty Robbins country-western classic, the rocket is designed as a 282-foot (86-meter) vehicle with a 15-foot (4.7-meter) diameter.
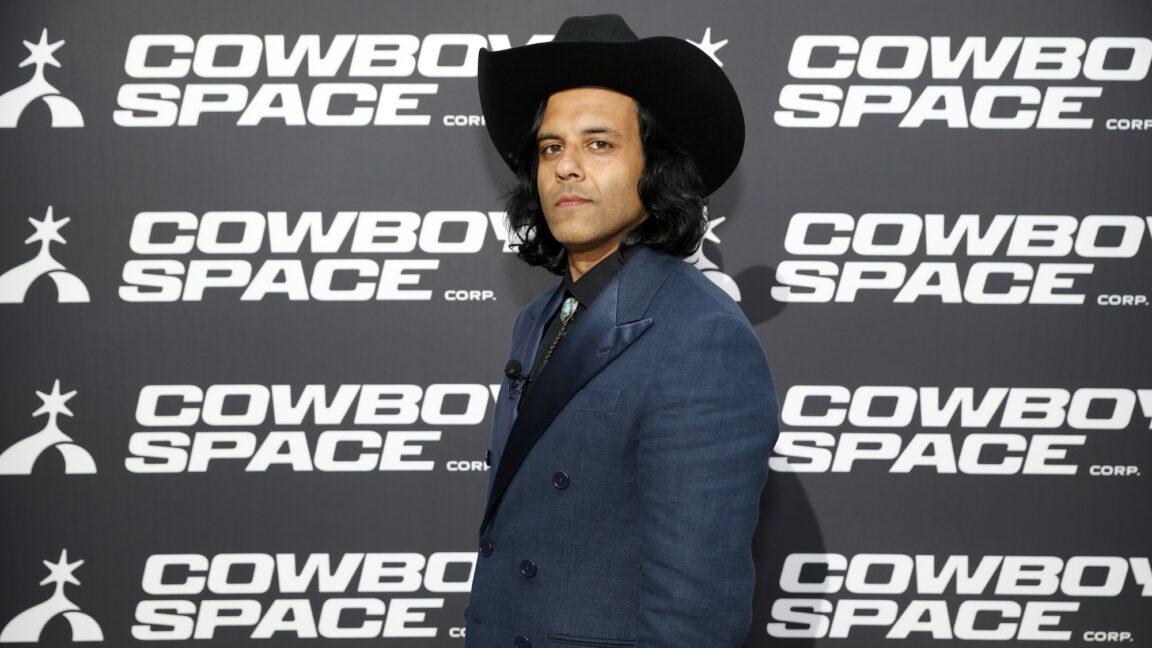
The engineering architecture for Big Iron relies on a methane-fueled engine, dubbed the "Clydesdale." The first stage will utilize a cluster of nine Clydesdale engines, with a single engine powering the second stage. According to the company, the vehicle is slated for its maiden flight before the end of 2028 and aims to deliver up to 18 metric tons (39,700 pounds) to low-Earth orbit (LEO).
Bhatt’s vision for the company, formerly known as Aetherflux, extends beyond simple payload delivery. The company plans to utilize the upper stage of the Big Iron rocket as a persistent orbital data center. Once in orbit, these stages would deploy solar arrays spanning the length of one-and-a-half football fields, integrating five racks of GPUs and six inter-satellite laser links. While the ambitious nature of the project has generated buzz, industry analysts note that the company faces a steep path toward flight readiness, particularly given the lack of flight-proven hardware currently available for public inspection.
Virgin Galactic and the Path to Suborbital Commercialization
In the suborbital space tourism sector, Virgin Galactic has taken a critical step toward resuming commercial operations. The first of the company’s "Delta-class" rocket planes, christened Apeiron, was transported from its Arizona manufacturing facility to Spaceport America in New Mexico this week. This move signals the start of a rigorous test campaign intended to pave the way for commercial flights, which the company currently projects will begin in the second quarter of 2027.
The transition to Apeiron follows the retirement of the VSS Unity vehicle in 2024. Engineering teams are now tasked with the installation of advanced avionics and flight control software, followed by a series of captive carry tests, drop tests, and eventually, powered flights exceeding the 80-kilometer Kármán line. With Blue Origin having scaled back its suborbital tourism efforts and SpaceX focusing its orbital-class Dragon spacecraft on other missions, Virgin Galactic remains the only entity positioned to offer consistent suborbital passenger flights in the near term. However, observers advise caution regarding the 2027 timeline, noting that aerospace development schedules are notoriously susceptible to delays.
The Struggles of the European Space Agency’s Themis Program
While the US market navigates a surge in commercial activity, the European Space Agency (ESA) is facing headwinds with its Themis reusable rocket demonstrator. On October 22, Geraldine Naja, ESA’s Director of Space Transportation, acknowledged that the program may fail to achieve its first flight before the close of 2026. Despite successfully completing two countdown rehearsals at the Esrange Space Center in Sweden, the project is being hindered by the harsh Scandinavian winter.
Themis, which is intended to test technologies for a future successor to the expendable Ariane 6, is powered by the methane-fueled Prometheus engine. Developed by ArianeGroup, the program has faced a long series of delays since its inception; the first low-altitude hop tests were originally slated for 2022. The inability to maintain the schedule set by Director General Josef Aschbacher in January—which targeted a Q1 2026 flight—underscores the technical and logistical complexities inherent in developing reusable, methane-fueled launch systems.
Government Funding and the Infrastructure Gap
Reflecting the government’s recognition of the growing need for reliable, diverse launch options, the Pentagon’s Office of Strategic Capital has extended a conditional $150 million loan to Stoke Space. This funding is earmarked for the construction of a second launch pad at Cape Canaveral Space Force Station. Stoke Space is currently developing its reusable Nova rocket, and the new infrastructure will accommodate the upgraded "Block 2" variant, designed to handle heavier payloads.
This infusion of capital follows a successful $1 billion Series E fundraising round in September, which brought Stoke Space’s total capital to $2.3 billion. The company aims to fly its Nova Pathfinder vehicle in 2027, with the more robust Block 2 following in 2029. Currently, the company’s innovative reusable upper stage is undergoing qualification testing in Moses Lake, Washington.
The Looming Launch Capacity Crunch
Despite the influx of private capital and new launch providers, industry leaders are voicing concerns that the US government may have overestimated the market’s ability to absorb rising national security launch requirements. During the 2026 Silicon Valley Space Week, executives questioned whether current infrastructure and company output could keep pace with demand, especially as the Space Force expands its pool of qualified launch providers.
A primary concern is the transition period as SpaceX moves away from the Falcon 9, which has served as a reliable workhorse for decades, toward the larger, more complex Starship system. Devin Papandrew, vice president of business development at Stoke Space, suggested that the government’s assumption that the "launch problem is solved" may have been a strategic miscalculation. United Launch Alliance (ULA) has similarly pointed toward a tight market, with company representatives suggesting that the supply-demand imbalance may not normalize until the early 2030s.
NASA and SpaceX: A Fraying Partnership?
A significant narrative emerging this month is the apparent cooling of the relationship between NASA and SpaceX. For over a decade, SpaceX has been the backbone of NASA’s logistics and crew transport capabilities. However, recent reports indicate that SpaceX’s strategic focus is shifting toward large-scale compute deployment and internal projects like the Starlink and "Starmind" constellations.
While SpaceX remains committed to the Artemis lunar lander program, there are indications of a broader pivot. The company has signaled its intention to cease Crew Dragon flights by 2030 and is prioritizing the deployment of the Starship architecture for its own commercial data service contracts. This change in priority suggests that NASA may soon find itself less central to the long-term strategic plans of its most critical private partner.
ULA’s Strategic Pivot and Return-to-Flight
Amidst these shifts, ULA is working to reassert its role in the launch market. The company has confirmed that its Vulcan rocket will return to flight on November 13, following a nine-month grounding caused by an anomaly in the solid rocket booster nozzles. The upcoming mission will carry 40 satellites for Amazon’s Project Kuiper, a vital test of the partnership between ULA and the retail giant.
Furthermore, NASA has tapped ULA to develop an "extended" version of the Centaur V upper stage for the Space Launch System (SLS). This development is designed to enable the Orion spacecraft to reach low-lunar orbit, a capability the current architecture lacks. NASA Administrator Jared Isaacman emphasized that this upgrade addresses long-standing propulsion and integration challenges, providing a more efficient alternative to the previously planned Exploration Upper Stage.
Future Outlook: Toward 2030
The overarching theme for the next four years is the scramble to modernize infrastructure. The US Space Force has explicitly stated a requirement for a third heavy-lift spaceport by 2030 to alleviate the congestion at Florida and California launch sites. However, as Lt. Gen. Philip Garrant of Space Systems Command noted, the path to establishing such a facility involves significant hurdles, including land acquisition, environmental regulation, and the logistical demands of a facility that is essentially a high-frequency, high-decibel airport.
As the industry enters the final quarter of 2026, the trajectory is clear: the era of relying on a singular launch provider is drawing to a close. Whether the current crop of startups like Cowboy Space and Stoke Space can meet their ambitious timelines will determine if the United States can maintain its strategic edge in space, or if the projected launch crunch will become a defining feature of the late 2020s.